Market
Market
Haliburton & Kawartha Cottage Market | 2026 Review & Outlook
Same as always: this IS NOT AI slop. I write this stuff.
After Muskoka, Parry Sound and the province as a whole, this is the last of this year’s reviews: Haliburton and Kawartha Lakes, two regions we report together. Sales here held steady. The supply picture didn’t, and the two regions’ prices went in opposite directions.
The Haliburton & Kawartha Lakes Cottage Market in a Nutshell
2026 so far
- Sales are flat, and below normal. 413 cottages sold from January to September, down 2.8% on 2025 and 13.8% below the 8-year average. Haliburton recorded 229 sales and Kawartha Lakes 184.
- Supply is at a record. Active listings averaged 331, up 9.9% and 87% above the 8-year average, and July’s 487 was the most in any month since 2018. Months of inventory is 7.2, about double the long-term 3.6.
- Prices split. The Haliburton median averaged $806K, up 5.0% on 2025. Kawartha Lakes averaged $815K, down 14.1%.
- More Kawartha cottages were pulled than sold. 221 Kawartha Lakes listings came off the market unsold from January to September, against 184 sales. In Haliburton, terminations fell 16% to 109.
2027 outlook
- Inventory stays historically high. Unsold cottages return in the spring on top of new listings.
- Prices drop 5-10%. With supply this far ahead of demand, the pressure is on price.
- The Cottage Forecaster. At the Q3 2026 update it reads Stable, but at the very low end, close to Correction. See the Forecaster.
How it compares
- In line with the province. Sales are down 2.8% here, against 0.5% for Ontario and 3.7% for Muskoka, while Parry Sound rose 18.7%. Read the Muskoka outlook.
What 2026 looked like
Sales held about steady. 413 waterfront cottages sold across Haliburton and Kawartha Lakes from January to September, down 2.8% on last year’s 425. Haliburton slipped 1.7% to 229, and Kawartha Lakes 4.2% to 184.
The longer view is weaker. Through an eight year lens, which includes the covid-era madness, we’re running 13.8% below normal, and 14.1% below 2018 and 2019.
About $382 million in cottages changed hands from January to September, almost exactly the same as last year.
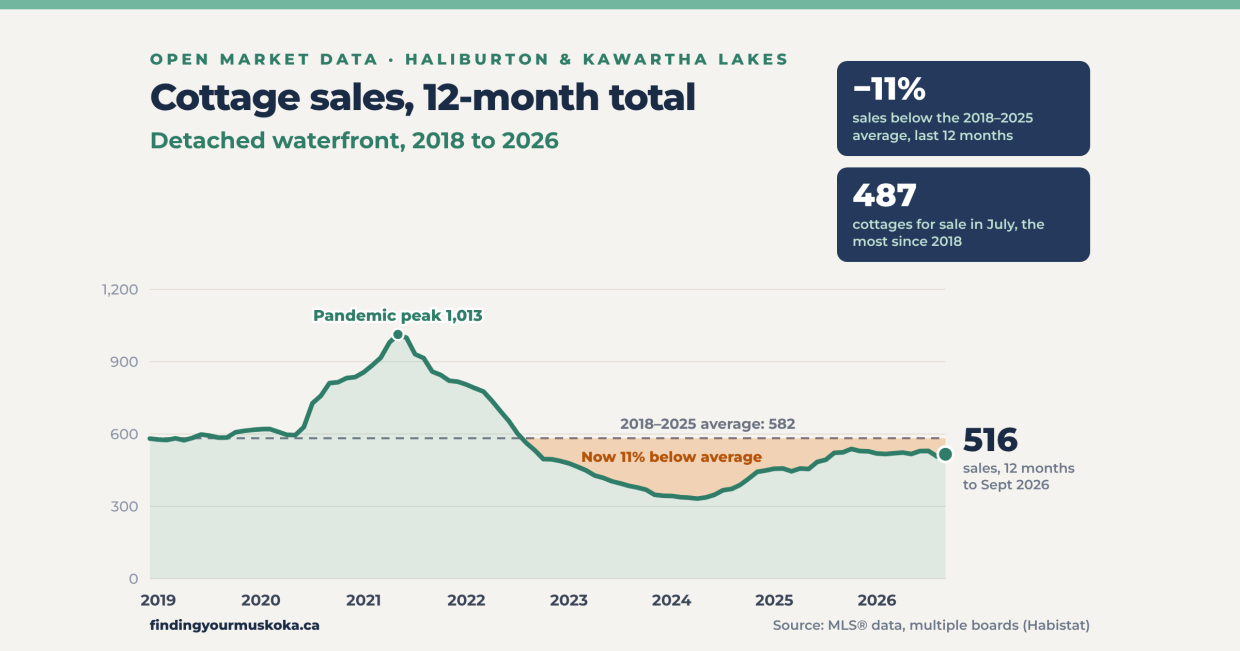
Haliburton & Kawartha Cottage Sales, 12-Month Rolling Total
Detached waterfront cottage sales in the 12 months ending each month, December 2018 to September 2026
| Period | Sales |
|---|---|
| 12 months to Dec 2018 | 581 |
| 12 months to Dec 2019 | 617 |
| 12 months to Dec 2020 | 836 |
| 12 months to Dec 2021 | 817 |
| 12 months to Dec 2022 | 488 |
| 12 months to Dec 2023 | 344 |
| 12 months to Dec 2024 | 449 |
| 12 months to Dec 2025 | 528 |
| 12 months to Sep 2026 | 516 |
Each point totals the 12 months ending then. The average line is the mean of the calendar years 2018 to 2025. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
The real story is supply. Active listings averaged 331 from January to September, up 9.9% on last year and 87% above the 8-year average. In July there were 487 cottages for sale across the two regions, the most in any month since 2018.
New listings, at 1,239, were down slightly on 2025’s 1,268, but still 30% above the 8-year average. Sellers aren’t listing faster than last year; the problem is that cottages already on the market aren’t selling.
Months of inventory is 7.2 this year, up from 6.4 and about double the long-term average of 3.6. That’s the highest since 2018.
The absorption rate shows it. About 14% of the cottages on the market sold each month, roughly 1 in 7. In 2018 and 2019 it was about 24%, or 1 in 4.
Haliburton & Kawartha Months of Inventory, 12-Month Rolling Average
Months of inventory: average active listings divided by average monthly sales, over the 12 months ending each month, December 2018 to September 2026
| Period | Months of inventory |
|---|---|
| 12 months to Dec 2018 | 3.9 |
| 12 months to Dec 2019 | 4.3 |
| 12 months to Dec 2020 | 1.7 |
| 12 months to Dec 2021 | 1.0 |
| 12 months to Dec 2022 | 2.4 |
| 12 months to Dec 2023 | 3.5 |
| 12 months to Dec 2024 | 5.9 |
| 12 months to Dec 2025 | 6.4 |
| 12 months to Sep 2026 | 7.1 |
Each point divides the average number of active listings by the average monthly sales over the 12 months ending then. Small sales counts in winter make single-month readings swing widely, so this is steadier than averaging monthly figures. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
What I see for 2027
The headwinds I described for Muskoka apply here too. The uncertainty tied to the United States is still the biggest weight on the market, and I don’t expect a meaningful change in direction while the current administration is in power. Interest rates are now going the wrong way too: the Bank of Canada raised its rate on October 28.
Terminations tell you where the pressure is. Across both regions, 330 listings came off the market unsold from January to September, down 4.1% on last year. But the two regions are very different. In Kawartha Lakes, 221 listings were pulled against 184 sales: 120 for every 100 sales, up from 111. In Haliburton it was 48 for every 100 sales, down from 56.
It’s no coincidence that Kawartha Lakes is also where prices fell. Sellers who couldn’t get their price pulled their cottages, and many of them will be back in the spring.
I expect inventory to remain historically high next year, and prices to drop 5-10%. The balance between supply and demand is pushing it that way.
Upside: If energy prices ease and the Bank of Canada can reverse course, steady sales and fewer new listings could start to bring inventory down from this year’s record.
Downside: If the Bank keeps raising rates and sales slip further, record inventory keeps building and the price pressure seen in Kawartha Lakes this year spreads to Haliburton.
Haliburton & Kawartha New Listings Against Sales, 12-Month Rolling Totals
New listings and sales of detached waterfront cottages in the 12 months ending each month, December 2018 to September 2026
| Period | New listings | Sales |
|---|---|---|
| 12 months to Dec 2018 | 1,014 | 581 |
| 12 months to Dec 2019 | 1,134 | 617 |
| 12 months to Dec 2020 | 991 | 836 |
| 12 months to Dec 2021 | 1,034 | 817 |
| 12 months to Dec 2022 | 978 | 488 |
| 12 months to Dec 2023 | 728 | 344 |
| 12 months to Dec 2024 | 1,224 | 449 |
| 12 months to Dec 2025 | 1,433 | 528 |
| 12 months to Sep 2026 | 1,404 | 516 |
Each point totals the 12 months ending then. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
Sales Against Terminations, by Region
Cottages sold, and listings taken off the market without selling, January to September, 2025 and 2026
| Region and year | Sales | Terminations |
|---|---|---|
| Haliburton 2025 | 233 | 130 |
| Haliburton 2026 | 229 | 109 |
| Kawartha Lakes 2025 | 192 | 214 |
| Kawartha Lakes 2026 | 184 | 221 |
Terminations are listings withdrawn or expired without a sale. Habistat’s termination counts rose sharply from 2024, apparently because of a change in how they are recorded, so they are compared with 2025 only. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. January to September of each year.
Prices tell two different stories. In Haliburton, the median averaged $806K from January to September, up 5.0% on 2025. In Kawartha Lakes it averaged $815K, down 14.1%. Over the last 12 months, Haliburton is up 4.4% and Kawartha Lakes down 9.8%.
Both are still well below their 2022 peaks: Haliburton by about a quarter, and Kawartha Lakes by about 17%.
A word of caution: both are small markets, with fewer than 100 sales a month even at the peak of summer, so a handful of large sales can move the median. Haliburton recorded no sales at all in January.
Sellers are getting 95.9% of asking, about the same as last year, and cottages are selling a little faster: a median of 31 days, down from 35.
Our Cottage Forecaster reads sold-listing data back to 2010 alongside economic signals and our own read from the docks. At the Q3 2026 update it reads Stable, but at the very low end of that range, close to Correction territory. It’s refreshed every quarter.
See the Cottage Forecaster →Haliburton and Kawartha Lakes Median Sale Price, 12-Month Rolling Average
Average of the monthly median sale prices over the 12 months ending each month, by region, December 2018 to September 2026
| Period | Haliburton | Kawartha Lakes |
|---|---|---|
| 12 months to Dec 2018 | $467K | $462K |
| 12 months to Dec 2019 | $495K | $476K |
| 12 months to Dec 2020 | $606K | $576K |
| 12 months to Dec 2021 | $827K | $797K |
| 12 months to Dec 2022 | $1.02M | $980K |
| 12 months to Dec 2023 | $802K | $852K |
| 12 months to Dec 2024 | $784K | $803K |
| 12 months to Dec 2025 | $765K | $916K |
| 12 months to Sep 2026 | $793K | $815K |
Each region is shown separately because medians can’t be combined. The source reports monthly medians only, so each point averages the monthly medians over the 12 months ending then. Haliburton recorded no sales in January 2026. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
The Market Headwinds Going Into 2027
Here is what I’m watching.
The U.S. trade dispute. Still the biggest weight on the market. Canadian consumer confidence was 47.3 in September, below its 2010 to 2026 average of 51.4, and foreign buyers still face the 25% NRST that has applied across Ontario since October 2022.
Record supply. Active listings and months of inventory are the highest since 2018. With sales flat, it will take time for buyers to work through it.
Unsold listings returning. 330 listings came off the market unsold from January to September, and in Kawartha Lakes they outnumbered sales. Many of them will come back in the spring, often at lower prices.
Rates, prices and jobs. The Bank of Canada raised its rate to 2.5% on October 28, its first increase since 2023, and warned that more hikes could follow. Its next decision is December 9. The hike pushes variable mortgage rates up right away. The 5-year bond yield, which sets fixed mortgage pricing, was 3.60% on October 2, close to its 52-week high of 3.71%. Inflation was 3.1% in September (2.2% excluding gasoline), driven by a 27.8% jump in gas prices, and Canada lost 68,000 jobs in September, with unemployment up to 6.5%.
Sources: Bank of Canada, Statistics Canada (CPI and Labour Force Survey), Ipsos consumer confidence and Habistat. Rates and yields as of the dates shown.
Haliburton & Kawartha Pricing Power: Sale-to-List and Days on Market
Sale price as a share of list price, and median days on market, sales-weighted over the 12 months ending each month, December 2018 to September 2026
| Period | Sale price as share of list | Median days on market |
|---|---|---|
| 12 months to Dec 2018 | 96.8% | 38 |
| 12 months to Dec 2019 | 96.0% | 39 |
| 12 months to Dec 2020 | 99.9% | 23 |
| 12 months to Dec 2021 | 110.7% | 12 |
| 12 months to Dec 2022 | 103.3% | 17 |
| 12 months to Dec 2023 | 96.7% | 28 |
| 12 months to Dec 2024 | 95.8% | 35 |
| 12 months to Dec 2025 | 95.6% | 37 |
| 12 months to Sep 2026 | 95.7% | 34 |
Both series are sales-weighted averages of the monthly figures over the 12 months ending then. The sale-to-list axis starts at 90%. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
Haliburton & Kawartha Active Listings, 12-Month Rolling Average
Cottages on the market, averaged across the monthly counts for the 12 months ending each month, December 2018 to September 2026
| Period | Active listings |
|---|---|
| 12 months to Dec 2018 | 190 |
| 12 months to Dec 2019 | 223 |
| 12 months to Dec 2020 | 115 |
| 12 months to Dec 2021 | 66 |
| 12 months to Dec 2022 | 98 |
| 12 months to Dec 2023 | 99 |
| 12 months to Dec 2024 | 221 |
| 12 months to Dec 2025 | 282 |
| 12 months to Sep 2026 | 304 |
Each point averages the monthly counts for the 12 months ending then. Source: MLS® data from multiple boards (Habistat), detached waterfront cottages, Haliburton and Kawartha Lakes combined, monthly. Rolling figures start in December 2018, the first full 12 months of comparable board coverage.
Using our data? Go for it.
A lot of agents, brokerages and journalists use our numbers and outlooks, and we’re glad they do. That’s why we publish them. All we ask is a credit and a link back to the source, so your clients can see where the figures came from.
Source: Finding Your Muskoka, findingyourmuskoka.ca
Need a chart, a number or a different cut of the data? Get in touch and we’ll help if we can.
About the data. The figures in this post come from The Habistat, an analytics tool powered by PropTx that combines MLS® data from nine Ontario real estate boards, and cover detached waterfront cottages, including water-access cottages, in Haliburton and Kawartha Lakes, combined. Board coverage was limited before 2018, so the long-term average is 2018 to 2025 (8 years) and the charts start there. Charts use 12-month rolling figures to smooth out the strong seasonality in cottage sales; the text compares January to September of each year. Months of inventory is average active listings divided by average monthly sales over each period. Median prices are shown for each region separately, because medians can’t be combined.
Figures use the latest data and can differ slightly from our Q3 report, because late-entered closings are added after publication. Only MLS®-listed sales are counted, so private and exclusive sales are not captured. Termination counts are compared year over year only. MLS®, REALTOR® and the associated logos are trademarks of The Canadian Real Estate Association. More at our Open Market Data page and the Cottage Forecaster.
How these figures are built: see our full methodology.
Questions or comments? Contact John Fincham, Broker @ RE/MAX Parry Sound Muskoka Realty Ltd. Brokerage